
Mounting fiscal strain in France has pushed its borrowing costs higher and rattled investor confidence in the eurozone’s second-largest economy. The fallout could spread well beyond French borders.
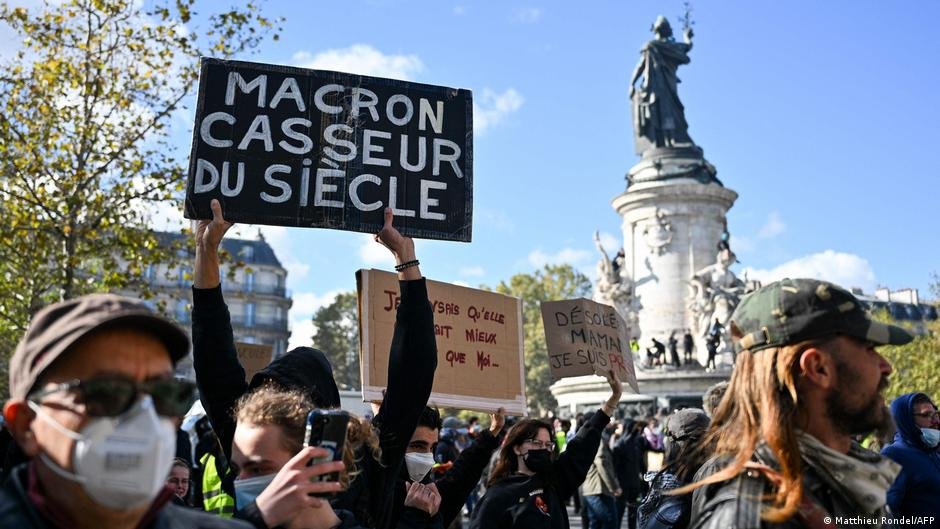
The trigger: an aging society coupled with soaring pension obligations that continue to squeeze public budgets. Proposed austerity steps aimed at narrowing the deficit have already sparked fears of street protests, complicating any government response.
Bond markets have taken notice. The spread between French and German 10-year yields has widened, signaling that lenders now demand a greater premium to hold French debt. That gap serves as a proxy for perceived risk inside the currency bloc.
France’s debt load has ballooned over decades, leaving little room for maneuver. As a result, political leaders face a bind: cut spending and provoke backlash, or borrow more and invite market punishment.
Presidential election uncertainty adds another layer of instability. Investors dislike unpredictability, and campaign promises to expand benefits rather than trim them have done little to soothe nerves. Meanwhile, Germany’s benchmark borrowing costs remain relatively low, amplifying the contrast.
Should market pressure intensify, French officials may find themselves forced into uncomfortable choices. The European Central Bank lacks a simple tool to rescue a single member state from a sovereign debt scare without broader consequences.
The bigger question now hangs over the eurozone itself. A French fiscal crisis would test whether the bloc’s safeguards, built after the Greek debt emergency, can withstand strain from one of its largest members. Markets, already nervous about growth, could reassess risk across the entire region.
France has not yet lost control of its financing. But the direction of travel worries policymakers in Brussels and beyond. If yields keep climbing, the pressure on Paris to deliver credible deficit reduction will intensify fast, before the next election cycle makes hard choices even harder.