
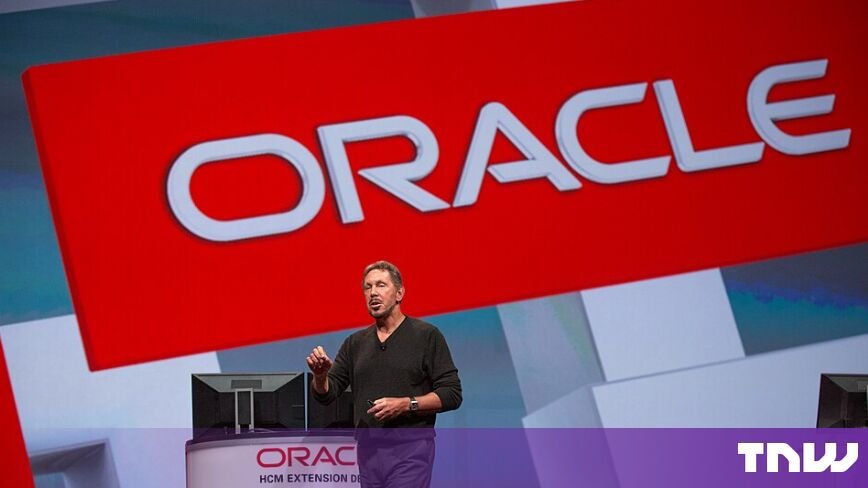
Larry Ellison, the founder who has embodied Oracle for nearly five decades, no longer headlines the company’s earnings calls or next month’s user conference. That spotlight now belongs to Clay Magouyrk and Mike Sicilia, elevated to co-chief executives last September.
The transition matters because Oracle’s business has transformed. Once defined by databases and applications, the company now sells cloud capacity at enormous scale. Meanwhile, Ellison, 82, remains chairman and chief technology officer with roughly 40% of the stock. His influence has not diminished. What has shifted is who explains the strategy.
Bloomberg first reported Ellison’s absence from earnings calls this year. Conference organizers also removed him from keynote billing. Previously, he missed few such events. One notable absence involved a yacht race.
Magouyrk joined Oracle in 2014 after six years at Amazon and AWS. He built Oracle Cloud Infrastructure into a network exceeding 100 public regions. His portfolio includes sovereign cloud services, a product category Ellison never had to pitch.
That sovereign offering has operated since June 2023. Oracle’s EU Sovereign Cloud runs regions in Frankfurt and Madrid, owned by separate EU legal entities and staffed exclusively by personnel based inside the bloc. Equinix hosts Frankfurt; Digital Realty hosts Madrid. Both remain isolated from Oracle’s commercial cloud at every layer, including networking, control planes, and identity services.
Amazon launched its own European sovereign cloud in Brandenburg this January, roughly two and a half years behind Oracle. Amazon’s AI assistant, however, does not appear on the published service list.
Meanwhile, Oracle faces financial strain. The company plans to spend $2.8 billion on job cuts while borrowing to fund data center construction. Headcount has dropped 13 percent within a year. Credit agencies have downgraded Oracle to one notch above junk status, driven by AI-related spending.
As a result, the executives on stage in Las Vegas next month will answer for a business model built on debt-fueled capacity expansion, much of it serving a single major customer. That burden, and that opportunity, now falls to the successors.