
Europe’s diesel supply crunch just hit a historic marker. External diesel and gasoil imports dropped to their lowest September level ever recorded, averaging only 1 million barrels per day.
Russian and Middle Eastern shipments accounted for nearly all of the decline, falling a combined 580,000 barrels per day versus the same month last year. Meanwhile, cargoes currently en route to Europe sit more than 25 percent below last year’s pace. October arrivals look equally weak.
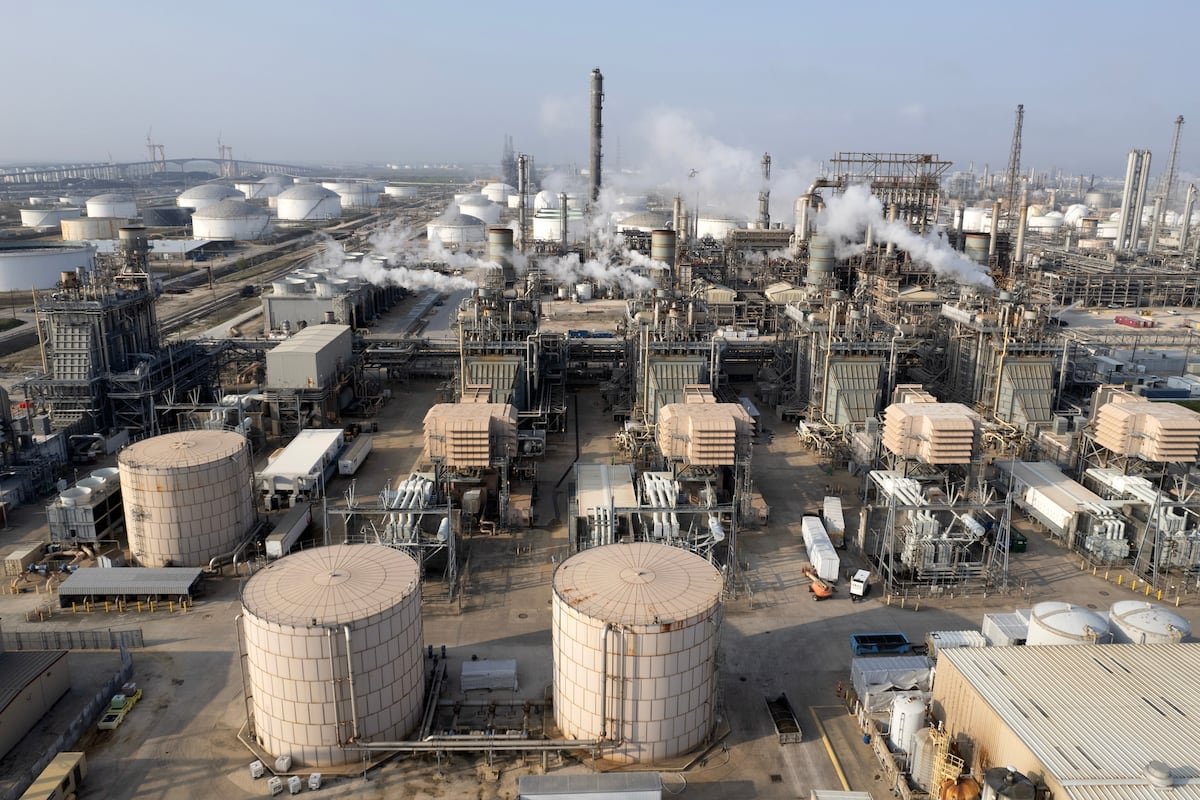
The region’s own refining output slid roughly 600,000 barrels per day in September after peaking in August. Strong margins pushed key maintenance work into 2027 at major facilities like Tarragona, Thessaloniki, and Gonfreville. As a result, the usual October maintenance peak likely already occurred last month, leaving European refineries with less scheduled downtime ahead but also less flexibility.
America remains Europe’s dominant external diesel supplier. The US delivered 41 percent of Europe’s external diesel in September at 400,000 barrels per day, slightly above year-ago levels but below August’s record dataset high of 445,000. Total US seaborne diesel exports stayed flat month on month near 1.6 million barrels per day. Latin American buyers now claim a growing share. PADD 3 refinery utilization has fallen for three straight weeks to 95.9 percent, signaling limited room for additional export volume.
Freight costs add another constraint. Houston-to-Amsterdam MR2 rates jumped 73 percent in a single week to hit $90 per ton on September 29. Talk of possible US export restrictions further clouds the supply outlook.
Asian barrels offer little relief. Chinese seaborne diesel exports have surged, but virtually none target Europe. Only one cargo loaded for the continent in September, the LR2 Torm Hermia, due in France late October.
Freight economics explain the gap. Zhoushan-to-Rotterdam LR2 rates reached their highest level in over two years, double last year’s figure. Growing volumes of Chinese diesel now move on larger LR2 vessels, with most landing in East Africa where buyers pay premiums to replace barrels lost from Red Sea refiners.
India stepped up deliveries to Europe by 50 percent month on month, reaching 240,000 barrels per day in September. That remains 23 percent below last September’s level.
ARA diesel inventories still sit 25 percent below seasonal norms. With no supplier positioned to fill the gap quickly, Europe heads into winter dependent on domestic refineries that have deferred maintenance for months, a setup that raises the odds of unplanned outages.