
As tech-transfer delegations work the partnering floor at BIO-Europe in Cologne this week, one metric separates serious players from slide-deck storytellers: actual drug assets licensed and funded spinouts moving between January 2024 and November 2026. Patent filings no longer impress anyone.
Every November, university technology-transfer offices descend on a European convention hall clutching slides bulging with invention disclosures, patents filed and startups formed. This year’s event runs 9 to 11 November at Koelnmesse, with digital partnering on 17 and 18 November. Asia-Pacific delegations have never been bigger.
Those slides measure activity, not conversion. A patent gathering dust is a liability. The question a licensing executive asks across the table comes down to this: when science leaves campus, does anyone pay for it, and how much?
The question carries new weight because Asia-Pacific has become pharma’s shopping destination. Chinese drugmakers alone signed 157 out-licensing deals worth US$135.7 billion in 2025, up from 94 deals worth US$51.9 billion the prior year, according to regulator data cited by the South China Morning Post. GlobalData counted US$7.86 billion of Korean innovator licensing value in just the first seven months of 2025. Those headlines name companies. The universities and institutes underneath remain invisible.
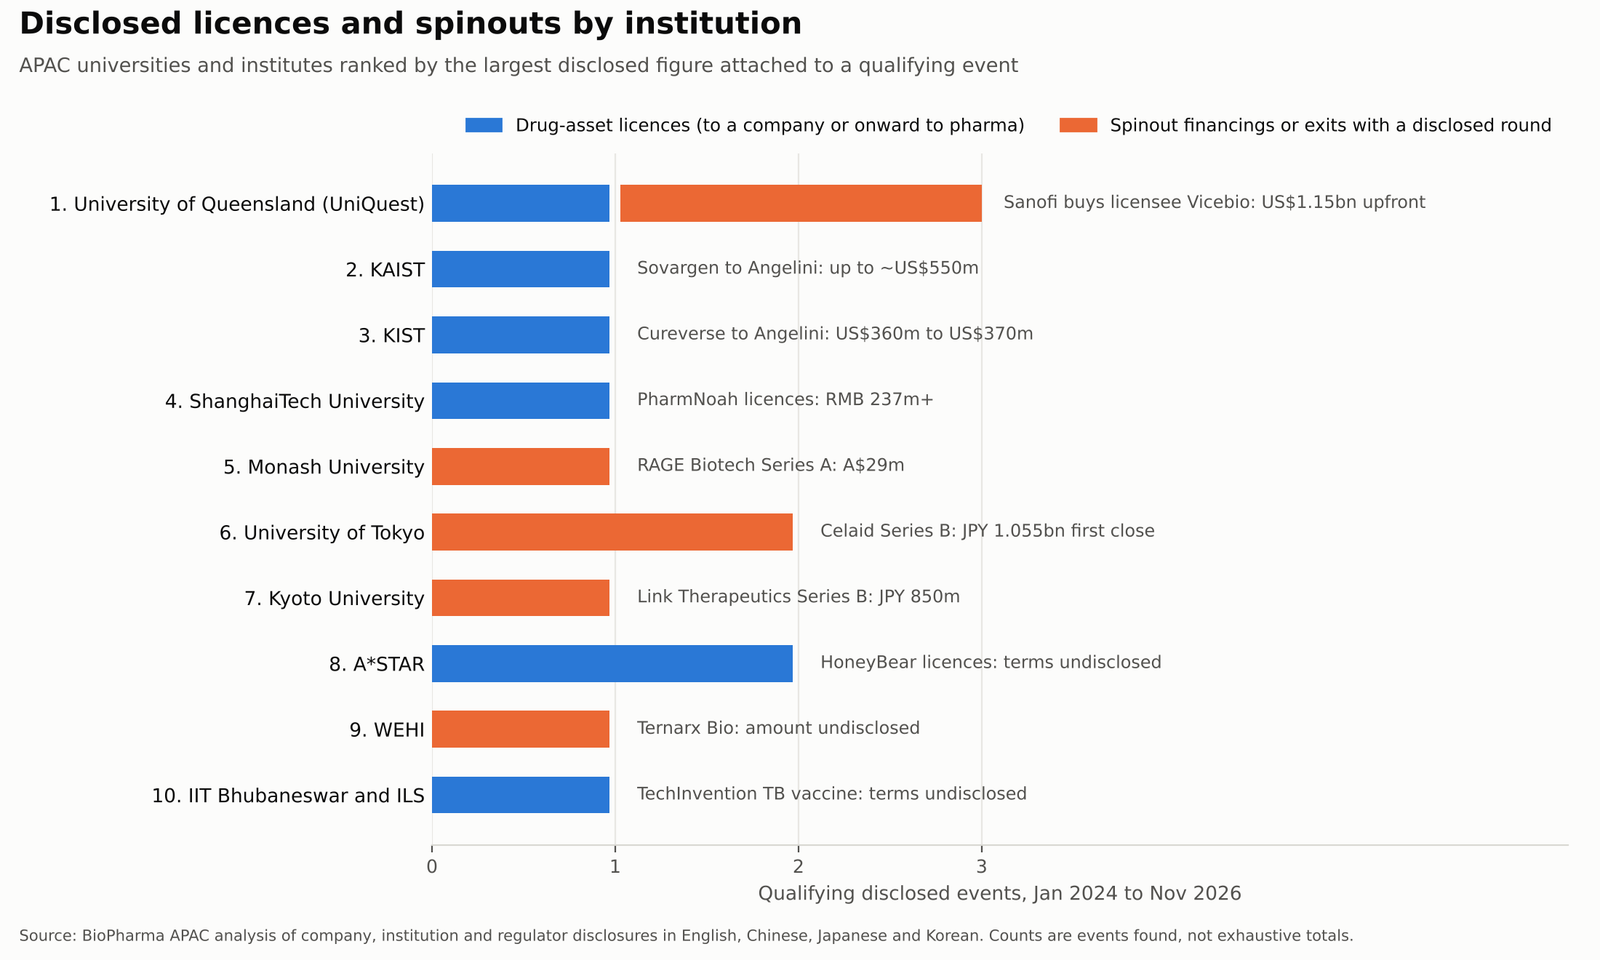
This ranking makes them visible. It counts disclosed drug-asset licences and disclosed spinout financings, not patent families. It records absences plainly where an institution’s silence kept it out.
**1. University of Queensland (Australia)**
UniQuest, the university’s commercialisation company, sits at the top because it displays the full arc every tech-transfer office pitches and few complete. The Molecular Clamp platform, invented by Keith Chappell, Daniel Watterson and Paul Young, stabilises viral surface proteins in their prefusion shape. UniQuest licensed it to Vicebio and kept equity. When Sanofi agreed to acquire Vicebio in July 2025 for US$1.15 billion upfront plus up to US$450 million in milestones, Queensland called it the largest deal ever involving Australian university IP.
What keeps Queensland from being a one-deal story happened next. In June 2026, UniQuest granted an exclusive licence for QED-203, a cancer candidate from Professor Greg Monteith’s research developed at QEDDI, to the Ellison Medical Institute in Los Angeles. QEDDI is the in-house medicinal chemistry group seeded by UQ and the Queensland government precisely so academic hits reach licensable candidate stage before anyone asks pharma to pay. Queensland does not sell disclosures; it sells molecules with development packages attached.
**2. KAIST (South Korea)**
KAIST qualifies on a single deal, but it represents the region’s cleanest example of basic science becoming a priced asset. Professor Lee Jeong-ho’s laboratory showed in Nature papers that some intractable epilepsies arise from acquired mutations in brain stem cells rather than inherited ones. The faculty spinout Sovargen then built SVG105, an antisense oligonucleotide targeting the mutated MTOR pathway.
In September 2025, Angelini Pharma took an exclusive global option to licence, excluding Korea and greater China. Undisclosed upfront, with milestones up to about US$550 million plus tiered royalties. Korean reporting credits the commercial turn to the 2023 arrival of Park Cheol-won, a former LG drug developer, as co-chief executive. The Korean-language coverage also adds a timeline English releases omit: Sovargen targets global clinical entry for SVG105 in 2027.
**3. Korea Institute of Science and Technology, KIST (South Korea)**
KIST researchers led by Park Ki-duk worked on CV-01 since 2014. The oral small molecule, acting on the Keap1 and Nrf2 pathway, entered Phase 1 in Korea in September 2024. A month later, Angelini Pharma optioned it for global rights outside Korea and greater China. Korea’s science ministry put the deal at US$370 million including milestones; BioWorld reported US$360 million.
The pattern matters. Angelini, a privately owned European mid-size building a brain health franchise, bought into two Korean institutional neurology assets within eleven months, both before proof of concept. That is a buyer profile academic offices across Asia should study: not big pharma, but focused specialists willing to take early CNS risk for ex-Asia rights.
**4. ShanghaiTech University (China)**
ShanghaiTech is the only mainland Chinese institution on this list, and the reason is disclosure rather than science. China’s companies signed 157 out-licensing deals worth US$135.7 billion in 2025, yet the academic origin of those assets rarely surfaces in English or Chinese filings. ShanghaiTech publishes deal values.
In September 2025, the university reported two agreements with PharmNoah Ininformigence Biotech worth more than RMB 237 million in total: an exclusive patent licence for Professor Bai Fang’s small-molecule anti-neuroblastoma candidates, and exclusive commercialisation rights to the team’s AI drug discovery platform. The Office of Technology Transfer states about 70% of its PCT and foreign patents have been licensed, with cumulative contract value above RMB 7 billion.
**5. Monash University (Australia)**
Monash earns its place on a single, well-documented round. Professor Merlin Thomas’s RAGE biology and the company’s splice-switching chemistry produced RB042, an inhaled oligonucleotide for COPD and related lung disease. RAGE Biotech closed a A$29 million Series A in November 2025, led by IP Group Australia and superannuation fund Hostplus, with Monash Ventures participating. BioWorld reported Phase 1 began in January 2026, roughly two months after the money closed.
The cheque-writer deserves attention. Hostplus is a pension fund, and its presence shows how Australian institutions pull domestic superannuation money into early biotech.
**6. University of Tokyo (Japan)**
Tokyo ranks on companies, not licences. Celaid Therapeutics, built on Professor Satoshi Yamazaki’s method for expanding haematopoietic stem cells outside the body, closed a Series B first close of JPY 1.055 billion in October 2025 from venture investors and AMED. TIME TRAVELER added JPY 100 million in December 2025.
The university counted 743 related startups by fiscal 2025’s end, up 105 in a year, including 39 IPOs and 79 acquisitions. That is the honest picture of Japanese academic drug creation: enormous company formation, modest cheques and very few out-licences priced in public.
**7. Kyoto University (Japan)**
Link Therapeutics grew out of a finding by Masahiro Shiokawa’s group that ulcerative colitis patients carry autoantibodies against integrin alpha-v beta-6. Its July 2025 Series B pulled in JPY 850 million from ITOCHU Technology Ventures, Kyoto iCAP, MUFG’s life science fund, SMBC Venture Capital and Kobe University Capital.
Some English-language wires reported the round as JPY 8.5 billion. The Japanese original reads 8.5 oku yen, which is JPY 850 million. This list uses the corrected figure.
**8. A*STAR (Singapore)**
A*STAR signed two licences with HoneyBear Biosciences of Taiwan in March 2025: an exclusive licence to antibodies from the Singapore Immunology Network for antibody-radionuclide conjugates, and a non-exclusive licence to a multicistronic expression vector. A*STAR also took equity, its first investment in a Taiwanese biotech.
The rank reflects the method, not the institution’s weight. A*STAR’s best-known asset, the antibody-drug conjugate EBC-129, has progressed into Phase 1b dose expansion but has not been licensed out. On disclosed numbers alone, Singapore’s flagship agency is quieter than its reputation.
**9. WEHI, Walter and Eliza Hall Institute (Australia)**
WEHI appears for what its seed fund has started to do. Ternarx launched in June 2024 as Australia’s first company dedicated to targeted protein degraders, born from a consortium of WEHI, the Children’s Cancer Institute and Monash. When a US investor wanted its prostate programme, WEHI Ventures co-invested to spin the asset into a US entity, Ternarx Bio, in February 2026.
That is a template other institutes can copy: keep the platform at home, let the first asset travel with a specialist investor, retain a slice of both. The weakness for ranking purposes is that none of the money is disclosed.
**10. IIT Bhubaneswar and the Institute of Life Sciences, Bhubaneswar (India)**
India’s academic system announces technology transfers frequently, but most are process know-how, diagnostics or reformulations. Many omit a date, a licensee or a defined asset. The Bhubaneswar tuberculosis vaccine agreement clears all three bars: a named HSP subunit candidate in DDA adjuvant, a named licensee in TechInvention Lifecare and a dated November 2025 signing.
For partnering teams meeting Asia-Pacific offices in Cologne this week, the practical questions follow from this list. Does the office take equity, and has any of it been realised? Has a spinout ever licensed onward, and to whom? Will the office publish the terms? The institutions above can answer at least one of those with a number. Next year, the list will be longer if more of their peers can too.