
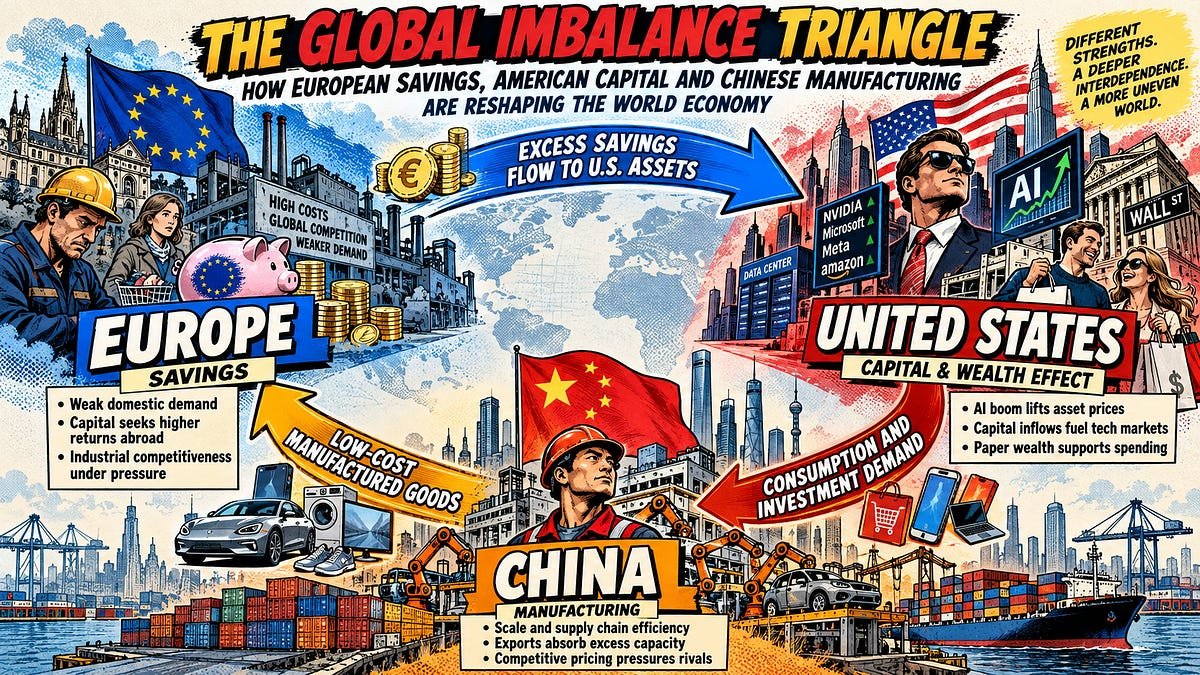
A widening three-way fracture now defines the global economy. Europe stockpiles wealth yet cannot convert it into homegrown breakthroughs, while America turns technological dominance into financial muscle, and China keeps expanding factory output even as local consumption lags.
These divergent models each function coherently in isolation. But combined, they produce structural imbalances that increasingly demand attention from policymakers and investors alike.
Europe sits on a paradox. The continent holds vast private capital, world-class financial institutions, and elite industrial firms. Yet in artificial intelligence, cloud infrastructure, and digital platforms, no European company approaches the scale of American technology leaders.
Mario Draghi’s 2024 competitiveness report put a number on the gap. The former European Central Bank president calculated the EU requires between €750 billion and €800 billion in additional annual investment to fund innovation, digitalization, energy transition, and industrial modernization.
The shortfall stems from deeper structural problems. Fragmented capital markets, cross-border scaling difficulties, high energy costs, demographic decline, and regulatory friction all suppress investment incentives.
As a result, European savings migrate outward through pension funds, insurers, and asset managers. US equities and bonds absorb much of that flow, drawn by liquid markets and the growth trajectory of leading tech firms.
However, framing this as European workers financing Silicon Valley misses the point. Household saving behavior reflects ageing demographics, pension design, income inequality, and economic uncertainty, not deliberate wage suppression.
The real issue remains Europe’s failure to recycle accumulated wealth into productive domestic capacity. Ownership of American AI stocks delivers financial returns, but the jobs, intellectual property, entrepreneurial ecosystems, and technical know-how stay elsewhere.
Across the Atlantic, the US leverages the world’s deepest capital markets alongside leadership in software, chip design, cloud computing, and artificial intelligence. Nvidia, Microsoft, Alphabet, and Amazon anchor expectations for the next technological wave.
The AI investment surge amplifies this advantage. Investors pay steep premiums for companies positioned to control future computing markets, while tech giants pour billions into data centers, accelerators, networking gear, and power infrastructure. Rising stock valuations then feed consumer spending through the wealth effect.
That mechanism, though, often gets oversimplified. Secondary-market share purchases transfer money between investors, not directly to companies. And wealth gains concentrate among upper-income households that hold most financial assets.
China occupies the third corner of this triangle. Decades of investment built a manufacturing ecosystem spanning raw materials, industrial machinery, electronics, and assembly. Deep supply chains, engineering talent, and domestic scale let Chinese producers compete aggressively on cost and speed.
The critical question now: will AI’s promised economic payoff justify the capital flooding into it? If revenues and productivity gains lag behind infrastructure spending, markets may revise expectations. Such a correction would ripple far beyond Wall Street, hitting the global hardware supply chains feeding the boom.