
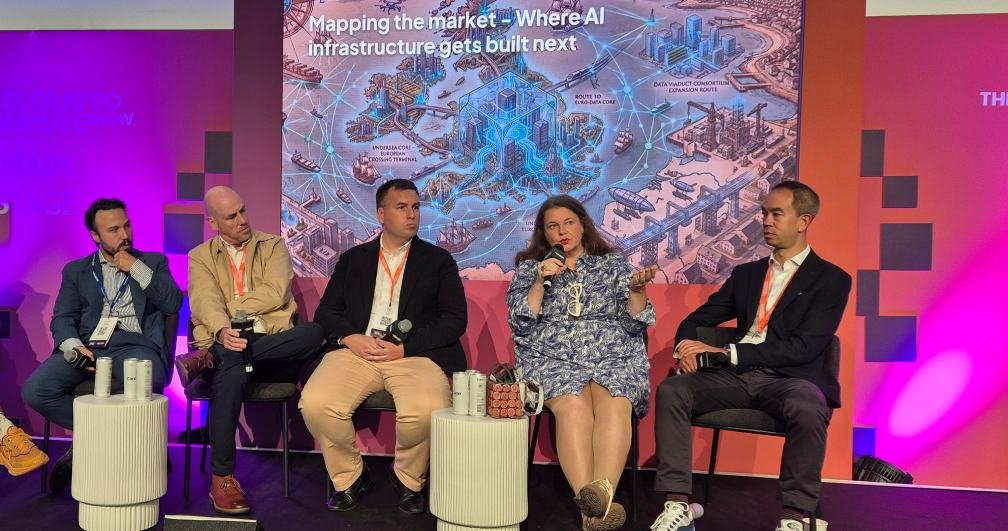
European AI infrastructure may lose the gigawatt-scale arms race to American hyperscalers, yet industry leaders gathered in London this week insisted that raw power capacity represents the wrong measure of victory. The region’s competitive edge likely sits in smaller inference hubs, faster deployment timelines, and serving software innovators before current technology assumptions become irrelevant.
Investment flows continue at staggering scale, of course. Brian Burns, partner at PwC, projected $31.6 trillion in cumulative spending across data centers, chips, and refresh cycles between now and 2050, with more than $1 trillion arriving this year alone. Nevertheless, Burns framed the real bottleneck as delivery capability rather than demand or capital. Supply chains, skilled workers, equipment availability, and operational processes will determine what actually gets built.
This distinction matters because announced projects and deliverable infrastructure diverge sharply. Burns coined the term “bragawatts” to describe capacity that exists only on paper. PwC now requires an identified site, grid connectivity, an off-taker, and a credible commercialization path before treating any project as real.
Rob Reid, director of hyperscale and strategic accounts at Zayo Europe, estimated that roughly five percent of speculative connectivity inquiries ever materialize. The remaining 95 percent never progress beyond rough cost estimates for hypothetical builds in fields outside Glasgow.
## Where real capacity lives
Nordic countries enjoyed early advantages from cheap power and cool climates, but viable sites now face scarcity. Reid noted growing activity in Iberia and France, where grid connection lead times can prove shorter. For Giorgio Sbriglia, CEO of Norwegian AI data center provider Terakraft AI, speed trumps all other factors.
“Where AI infrastructure gets built is where you can go fast,” he said. Power reservations alone no longer suffice.
Norway has tightened its allocation process by requiring financing plans, business milestones, and evidence of viable projects. As a result, much of the competitive maneuvering involves hoping rivals miss deadlines so their power allocations become available.
Meanwhile, Chris Yiu, Meta’s director of public policy for Northern Europe, illustrated the scale gap by comparing the company’s Hyperion campus in Louisiana, targeting one gigawatt initially, to a footprint stretching from central London to the O2 arena in North Greenwich. Europe cannot realistically compete on frontier-scale training infrastructure over the next five years.
Yet the smarter play may lie elsewhere. OpenUK CEO Amanda Brock argued that most businesses will adapt existing models rather than train new ones, while others build agents and frameworks around them. Edge inference facilities, distributed closer to users and regulators, could become Europe’s strongest opportunity.
Sbriglia cautioned against building for today’s requirements when more efficient chips may arrive before projects reach operation. Both he and Reid selected France as their preferred European build location today, citing policy stability, infrastructure, and talent. The U.K. retains hope through its technical workforce, according to Brock. Success will favor whoever combines power, connectivity, customers, and political will fastest.