
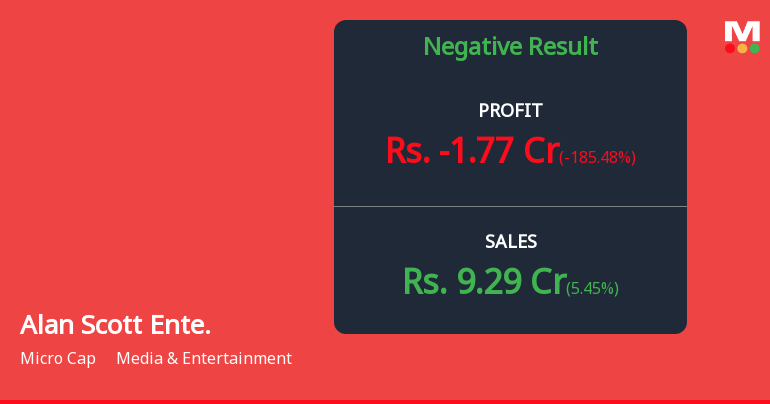
Alan Scott Enterprises confronts an escalating financial emergency after posting a ₹1.77 crore consolidated net loss for Q2 FY27, a 185.48% year-on-year collapse that exposes fundamental cracks in its business model. The losses mounted even as revenue climbed to ₹9.29 crores, the highest quarterly figure in the company’s recent record.
The disconnect between top-line growth and profitability has become impossible to ignore. Revenue improved 5.45% from the year-ago period, yet operating profit swung violently negative at ₹0.67 crores. That translates to a negative operating margin of 7.21%, a brutal reversal from the 6.81% positive margin recorded in Q2 FY26.
**Spiraling Costs, Shrinking Margins**
Personnel expenses stand at the center of the deterioration. Employee costs ballooned 64.34% to ₹2.35 crores from ₹1.43 crores in the corresponding quarter last year. Meanwhile, interest obligations remained heavy at ₹0.47 crores, while depreciation consumed another ₹0.98 crores.
As a result, the profit after tax margin cratered to negative 23.14%, down sharply from negative 10.33% in Q2 FY26.
The company’s return metrics tell an equally grim story. Return on equity sits at negative 24.80%, while return on capital employed registers negative 15.50%. Both figures indicate active shareholder value destruction.
**Cash Flow Crisis Deepens**
Operating cash flow turned sharply negative at ₹6.00 crores for FY26. Investing activities drained another ₹5.00 crores. Consequently, the company relied entirely on financing inflows of ₹12.00 crores to stay afloat, funds that likely came from fresh equity issuance.
This pattern of funding operations through dilution rather than generated cash remains deeply concerning. Share capital jumped from ₹3.63 crores in March 2025 to ₹5.72 crores in March 2026, confirming the reliance on external capital.
**Valuation Divorced From Reality**
Despite these mounting losses, Alan Scott commands a price-to-book value multiple of 17.02x, roughly four times its peer average. The EV-to-EBITDA ratio sits at an astronomical 199.48x. Meanwhile, institutional ownership remains negligible at just 0.50% combined across FIIs and mutual funds.
Promoters increased their stake to 64.75% in September 2026, but the stock now trades below all key moving averages, suggesting weakening momentum. Annualized volatility of 53.61% compounds the risk profile.
Management faces a stark choice: engineer a genuine operational turnaround or face continued value erosion paired with relentless dilution. Without demonstrable progress toward breakeven, the current premium pricing appears unsustainable.