
Defense technology has become a magnet for private equity capital, with firms channeling billions into the sector as military budgets swell and global tensions escalate.
Growth-stage private equity deals in defense hit $4 billion during the first nine months of 2026, according to PitchBook data. That figure stood at just $500 million for all of 2024. The surge signals a dramatic repositioning by investors who once avoided the sector entirely.
As defense startups mature, analysts expect private equity, debt financing, and other capital sources to play a larger role bridging the gap between innovation and industrial-scale manufacturing. Venture capital alone cannot fund the production expansion many companies now require.
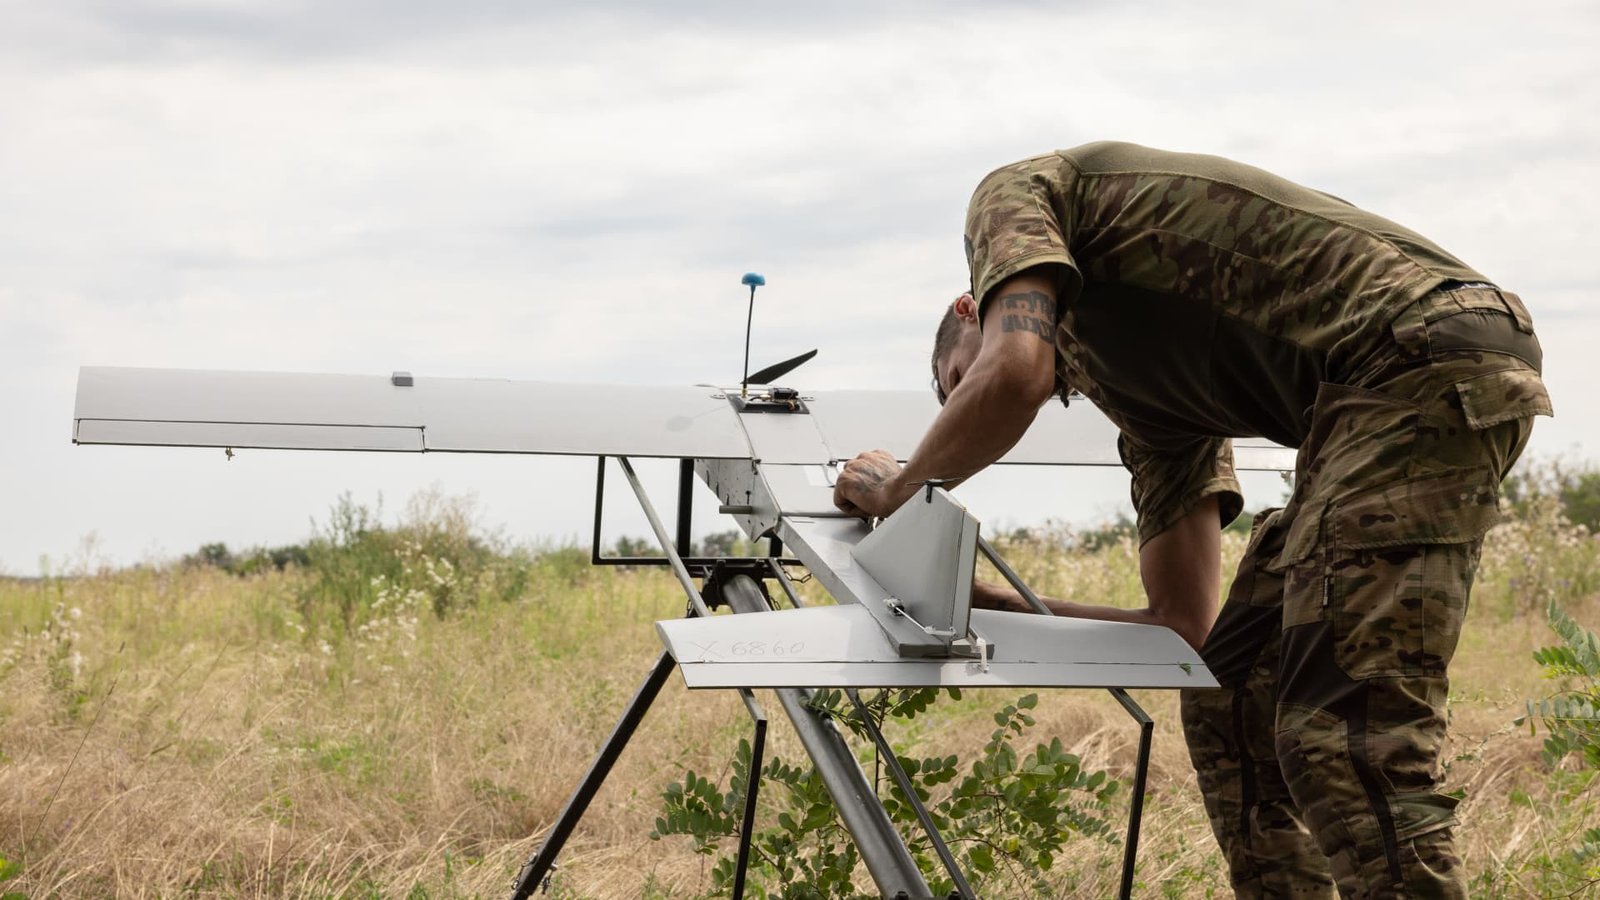
Geopolitical conflicts and military modernization efforts have created openings for firms developing autonomous drones, missile defense systems, and satellite technology. A White & Case survey of 250 senior decision-makers at U.K. defense companies found 97% anticipated seeking major external funding within 12 months.
“Private capital is now playing a critical role in the financing of defence technology companies,” said Daniel Turgel, a partner at White & Case.
Sovereign wealth funds, family offices, and both private equity and venture capital firms have all stepped up investments. Turgel noted many of these investors faced restrictions or hesitation just a few years ago.
**A new class of investors**
Venture capital flows into defense technology have also accelerated. Startups across NATO and allied nations raised $27.1 billion through September, nearly doubling the full-year 2025 total, per Dealroom and Resilience Media.
The line between venture capital and private equity continues to blur. PitchBook lead industrials analyst Jim Corridore observed that PE firms are moving into territory once dominated by VC. Defense PE growth deals climbed from 15 in 2024 to 31 in 2025 and 48 through September 2026. Growth investments represented 41% of defense PE deal value in 2026, up from 3% two years earlier.
Advent International committed up to $1 billion to next-generation defense technology in March, backing autonomous systems developers Shield AI and Saronic. Managing partner Shonnel Malani said roughly three-quarters of that capital has already been deployed. Advent prioritizes proven technologies with customer validation over purely financial metrics.
**Bubble concerns**
Rising valuations have sparked worries about speculation. Malani acknowledged defense tech companies increasingly trade on technological promise rather than revenue or orders, leaving “considerable room for interpretation” on worth. He warned an investment bubble could emerge, describing “a lot of froth in the system.” Advent has walked away from several deals where valuations became “silly.”
Meanwhile, Corridore pushed back on overheating concerns, citing growing defense budgets and steady revenue streams that support long-term bets.
French firm Weinberg Capital Partners sticks to traditional buyouts of profitable defense suppliers with established products and positive cash flow. Partner Lionel Mestre sees consolidation opportunities across Europe’s fragmented supply chain and noted institutional attitudes toward defense investing have shifted significantly, especially since President Donald Trump’s return to the White House renewed pressure on European military spending.
**Can the boom deliver returns?**
Both Advent and Weinberg see opportunities to help defense companies scale production while providing industry connections and government access. However, exits remain a challenge. PitchBook counted 504 defense PE deals since 2021 against only 101 exits. IPOs represented 70% of defense PE exit value through September 2026, leaving investors vulnerable to stock market volatility.